This site uses cookies. By continuing to browse the site, you are agreeing to our use of cookies. Privacy Policy
Okay, thanks
Hedged equity as a liquid alternative uses an options-based equity strategy — specifically Swan Global Investments’ Defined Risk Strategy (DRS), in continuous operation since 1997 — as a permanent alternatives allocation that stays invested in the equity market while actively managing downside risk through LEAPS put options. Unlike most liquid alternative funds, which have a median inception date of August 2022 and are often adopted during crises and abandoned in recoveries, the DRS is designed as an “Always Invested, Always Hedged” through-cycle allocation launched in July 1997. In historical analysis from July 1997 through December 2025, a 20% DRS sleeve in a traditional 60/40 portfolio produced higher returns, lower volatility, and a better Sharpe ratio than the same allocation to the Morningstar Multistrategy liquid alt category average. Past performance does not guarantee future results.
“Most liquid alternatives are a ‘sometimes’ asset class — adopted in crises, abandoned in recoveries. Swan’s Defined Risk Strategy is built to be held through the full cycle: Always Invested, Always Hedged, since 1997.”
The liquid alternative role explored in this article is one of the core applications of institutional hedged equity — defined by combining uncapped equity participation with actively managed downside risk, designed to function as a permanent portfolio allocation rather than a crisis hedge.
Most liquid alternative funds fail a simple test: they cannot be held through a full market cycle — adopted in crises, abandoned on recoveries, and gone before the next bear market arrives.
The liquid alternatives category has a lifecycle problem. Advisors and allocators adopt alternative strategies after a crisis, then abandon them when markets recover. The result: approximately 2,100 liquid alternative funds have gone extinct over the past 20 years, even as 1,536 remain active today.
The question for any serious allocator is not which alternative fund to own—it’s whether hedged equity, used as a permanent allocation, solves the problem that makes traditional liquid alternatives so difficult to buy and hold.
This article, the third in a four-part series, examines how hedged equity functions as a structurally distinct liquid alternative sleeve: maintaining meaningful equity participation in bull markets while actively managing drawdown risk in bear markets. By design, it is built to be held through the full cycle, not just the crisis.
Our portfolio managers and analysts are dedicated to creating relevant, educational Articles, Podcasts, White Papers, Videos, and more.
Investors want all three simultaneously — full upside participation, meaningful downside protection, and low fees — and no single liquid alternative strategy reliably delivers all three.
Part of the problem is that investors often have unrealistic expectations for their liquid alternative investments. It seems like some investors want their alternative portfolio allocations to have the following features:
While these features are desirable, it seems unlikely that any single fund or investment strategy will feature all three of these characteristics simultaneously. The old saying “There is no free lunch” holds true in alternative strategies.
That said, many liquid alternative strategies seek to maximize the tradeoff between upside capture and downside risk minimization. Given those criteria, Swan’s Defined Risk Strategy (“DRS”) is one of those strategies.
Hedged equity solves the trade-off by keeping the portfolio fully invested in the equity market while using actively managed put options to flatten losses in bear markets — without capping gains in bull markets.
The Defined Risk Strategy (DRS) is designed to mitigate losses when the market is down significantly, while still providing meaningful up-market participation. The driving idea behind the DRS is that large bear markets are too painful to endure, so the DRS is engineered to have a different risk-return profile than a traditional long position.
The Defined Risk Strategy is a hedged equity solution that utilizes long-term put options to manage the upside/downside trade-off. Moreover, these put options are actively managed according to our time-tested process. Rather than being held to expiration, the DRS’s put options are sold when they still have value. The put options are sold well before expiration and new put options are purchased at current market levels as part of the actively managed “re-hedge” process. The re-hedges typically occur 1) near the end of the calendar year, halfway through the put options’ lifecycle, 2) following a deep market sell-off when the options are “in-the-money” and profitable, or 3) following a market run-up to ratchet up the levels of the hedge.
The strategy has been active since 1997 and has successfully weathered the largest bear markets this century: the Dot-Com Bust and the Global Financial Crisis, as well as other periods of major market stress like the 2010 Flash Crash, the Covid-19 selloff of 2020, the inflation bear market in 2022, the 2025 Tariff Tantrum and more.
One of the key charts that convey this message is the one below, referred to as the “Target Return Band”. We believe that our Target Return Band is a very appropriate prism through which our performance can be viewed. The three main elements of the Defined Risk Strategy are charted in this band:

Source: Swan Global Investments Source: Swan Global Investments and Morningstar. * 1997 annual returns are total returns (i.e. not annualized) from July 1997 through December 1997, consistent with implementation of the Swan Defined Risk U.S. Large Cap Composite (DRS US LC), shown net of all fees. The S&P 500 Index is an unmanaged index and cannot be invested into directly. Prior performance is not a guarantee of future results. NOTE – this chart is for illustration purposes, not a guarantee of future performance. The charts and graphs contained herein should not serve as the sole determining factor for making investment decisions.
Essentially a profit-loss diagram, this chart shows:
It is our goal that returns of the DRS will be within or above the blue shaded area. More often than not, they have been.
That said, there are many different ways to manage the upside/downside trade-off. Morningstar currently has two broad groups called “Nontraditional Equity” and “Alternative”, which have four and eight specific categories within them, respectively.
The liquid alternatives universe spans 12 Morningstar categories, $627.58 billion in AUM, and 1,536 active funds — alongside approximately 2,100 that no longer exist.
The categories within these two broad groupings are as follows:
| Category | AUM ($bn), 12/31/25 | Fund Count, 12/31/25 | |
|---|---|---|---|
| Non-Traditional Equity | |||
| Derivative Income | $165.05 | 281 | |
| Equity Hedged | $65.11 | 166 | |
| Defined Outcome | $78.79 | 441 | |
| Long-Short Equity | $31.31 | 103 | |
| Alternative | |||
| Macro Trading | $9.07 | 44 | |
| Event Driven | Relative Value Arb | $21.98 | 20 |
| Multi-Strategy | $47.39 | 121 | |
| Equity Market Neutral | 41 | ||
| Systematic Trend | Multi-Asset Leveraged | $14.48 | 52 |
| Digital Asset | $146.21 | 141 | |
| $627.58 | 1,536 | ||
Source: Morningstar Direct
Understanding liquid alternatives is very difficult. First, there is a very wide dispersion of strategies. Second, many strategies are complex or have unique drivers of returns.
I could go on, but the point is that broad definition of “liquid alternatives” encapsulates many different strategies and trying to understand all the factors at play becomes very difficult to manage.
A 20% DRS allocation in a traditional 60/40 portfolio historically produced higher returns, lower volatility, and a better Sharpe ratio than the same allocation to the Morningstar Multistrategy liquid alt category average — over the same 28-year period.
The bias some investors have against liquid alts is based on data suggesting it simply isn’t worth the extra time, complexity, and additional cost of including liquid alternatives into a basic, traditional portfolio. The data below illustrates the impact of adding the Morningstar category average of diversified Multistrategy funds (listed in the table as “Liquid Alts”) to a traditional 60% S&P 500, 40% bond portfolio. 10% is redirected from both the equity and bond allocations, giving an overall 20% allocation to the Multistrategy category. For comparison, the same changes were made using Swan’s Defined Risk Strategy. Data shown is from the inception of the DRS, July 1 1997, through May 30, 2026.
|
|
Return |
Standard Deviation |
Beta |
Sharpe Ratio |
|
50% S&P 500/20% Liquid Alts/30% Bloomberg Agg |
7.03% |
9.20% |
0.59 |
0.52 |
|
50% S&P 500/30% Barclays Agg/20% Swan US LC |
7.62% |
9.16% |
0.58 |
0.62 |
|
60% S&P 500/40% Bloomberg Agg |
7.74% |
9.61% |
0.61 |
0.54 |
|
S&P 500 |
9.67% |
15.44% |
1.00 |
0.48 |
Source: Morningstar Direct, Zephyr StyleADVISOR and Swan Global Investments. Data based on historic returns of a 60/40 blended composite and the Swan Defined Risk US Large Cap Composite net of fees, from 7/1997 to 5/30/2026, and assume no portfolio withdrawals. Morningstar Multistrategy funds are defined as portfolios that offer investors exposure to two or more alternative investment strategies (such as options, macro trading, event-driven, relative value, and systematic trend) through either a single-manager or multi-manager approach. To qualify for this category, alternative strategies must comprise greater than 30% of the fund’s gross exposure, with the majority of assets typically allocated to these alternatives. Results in the table are the best, worst, and average annualized returns, based on month-end returns, for every rolling period listed within the overall time frame of July 1st, 1997 to May 30, 2026. Prior performance is not a guarantee of future results and there can be no assurance, and investors should not assume, that future performance will be comparable to past performance. This chart is for illustration purposes, not a guarantee of future performance, and should not serve as the sole determining factor for making investment decisions.
Using a broad-based index as a proxy for liquid alternatives, it is easy to see why some investors remain unconvinced. The returns are less, the risks are higher, and the Sharpe ratio is lower than the traditional 60/40 portfolio.
However, when using a 20% allocation to Swan’s Defined Risk Strategy, the reverse is true: returns have historically been higher, risks lower, and the Sharpe ratio shows an improvement over the traditional 60/40.
The lack of compelling results from many liquid alternatives leads directly to the next section, which discusses the high level of “failed” or shut-down liquid alt mutual funds and ETFs.
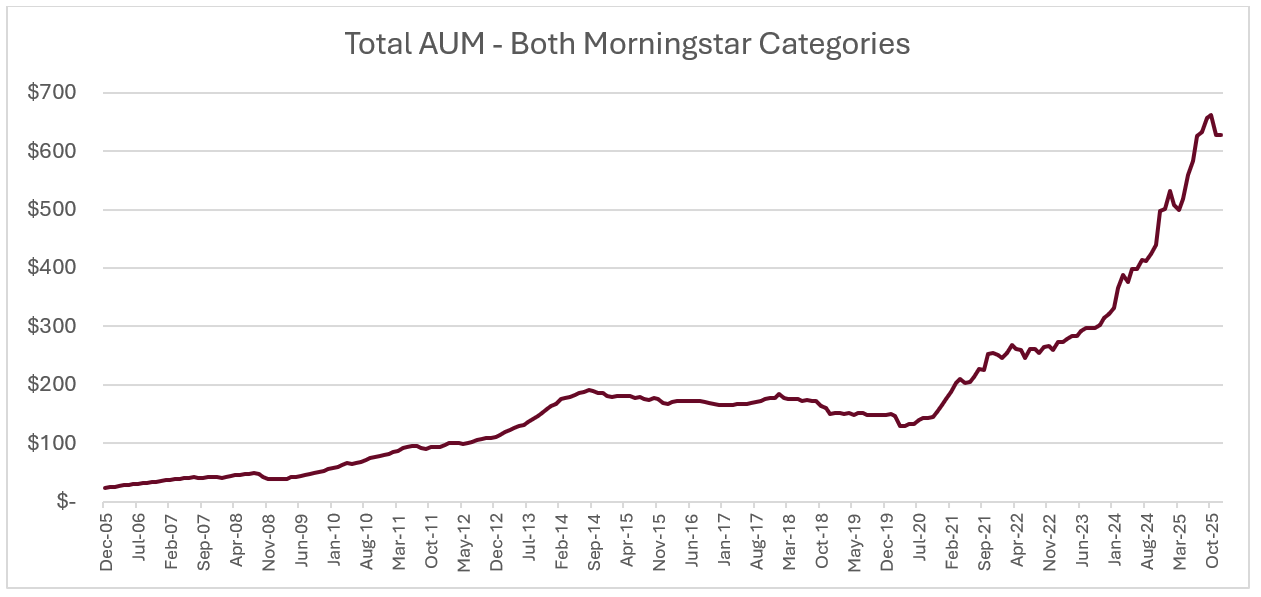
Approximately 2,100 liquid alternative funds have gone extinct over the past 20 years — even as 1,536 remain active today. The lifecycle pattern is consistent: assets surge after crises and drain in recoveries.
While the return drivers of different alt strategies vary, broad growth in liquid alternatives assets under management was driven by two, macro-level market events. The first was following the Global Financial Crisis of 2007-09 and the second was following the Covid-19 Pandemic. Both crises were marked by a steep market sell-off followed by an era of ultra-loose monetary conditions.
Source: Morningstar Direct, data as of 12/31/2025.
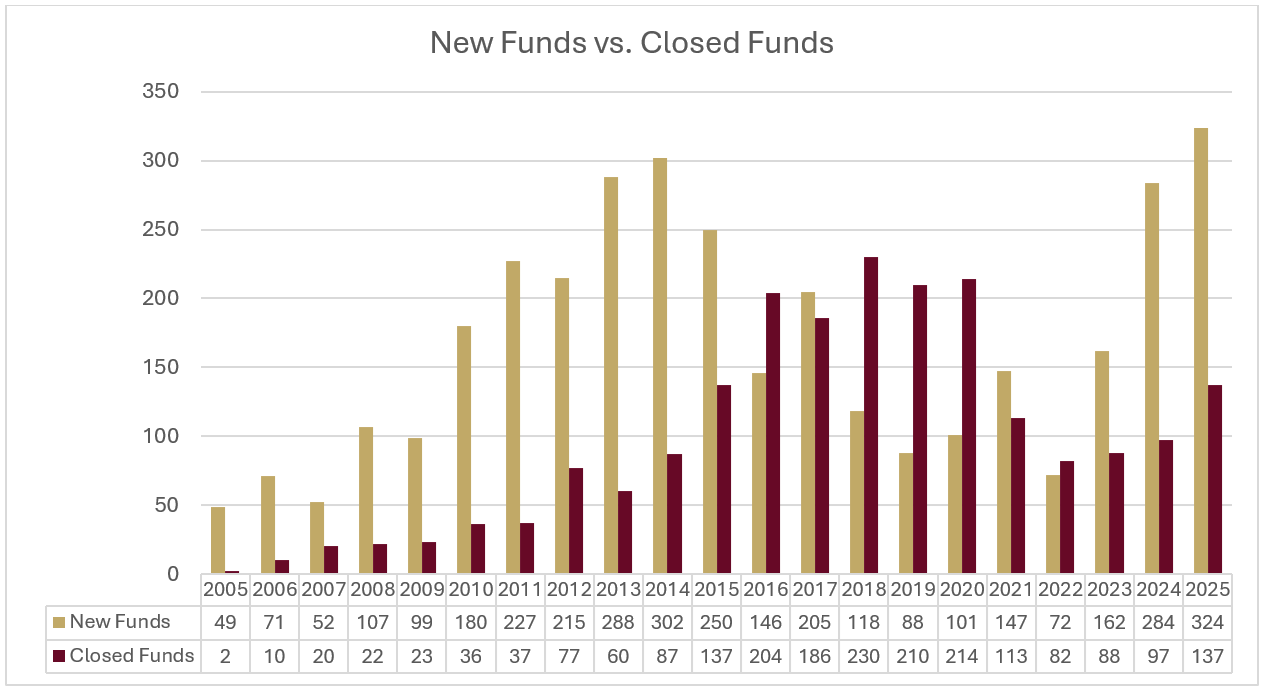
The liquid alternative fund space has also been marked by periods of shrinkage and consolidation. Although there are 1,536 funds in existence today, an in-depth study of Morningstar Direct’s data shows that around 2,100 alternative funds have gone extinct over the last 20 years.
Source: Morningstar Direct, data as of 12/31/2025.
The life cycle of liquid alternative funds is not hard to discern:
Often viewed as a “sometimes” asset class rather than an “always” asset class, the unfortunate reality then is that portfolios rarely contain a permanent liquid alternatives allocation. During equity bull markets, investors tend to abandon strategies that drag down overall portfolio performance too much. The lesson appears to be that if an alternative fund is to survive, if it is to be accepted as an “always” investment, it needs to provide enough upside market participation during bull markets.
The DRS is built for permanent allocation — not tactical deployment — because it is designed to justify its place in a portfolio in bull markets, not just bear markets.
Due to the vicious Darwinism in liquid alternatives, the median inception date for active funds in this category is only August 2022. That means half of the funds in this broad category have not been battle-tested by the Dot-Com Bust, the Global Financial Crisis, or even the inflation bear market of 2022. The only significant market sell-off to occur since August 2022 was the brief “tariff tantrum” of early 2025.
On the other hand, Swan has been managing the Defined Risk Strategy for almost three decades. As an “Always Invested, Always Hedged” strategy, the DRS invests in the market and seeks meaningful participation during bull markets. The strategy is hedged in an attempt to mitigate the downside risk in bear markets. By balancing upside market participation with downside risk mitigation across nearly three decades and five major market crises, the Defined Risk Strategy has earned consideration by many as a permanent alternative portfolio allocation — not a tactical one.
To see how hedged equity functions in other portfolio roles, continue the series:
Q1: What is a liquid alternative investment?
A liquid alternative is a registered investment fund (mutual fund or ETF) that employs strategies traditionally associated with hedge funds — such as long-short equity, options strategies, or macro trading — while offering daily liquidity, lower minimums, and regulatory oversight. Morningstar currently tracks 12 liquid alternative categories with more than $627 billion in combined AUM and 1,536 active funds.
Q2: Why do liquid alternative funds have such high failure rates?
Liquid alternative funds have historically followed a crisis-adoption, recovery-abandonment cycle: assets flow in after market crises and flow out when long-only equity recovers. Morningstar Direct data shows approximately 2,100 liquid alternative funds have gone extinct over the past 20 years, even as 1,536 remain active — a failure and consolidation rate that reflects both underperformance and investor behavior. Strategies that cannot provide meaningful upside participation in bull markets tend not to survive to the next crisis.
Q3: How is hedged equity different from a liquid alternative fund?
Most liquid alternative strategies trade off upside participation for downside mitigation — long-short funds short individual stocks, market-neutral funds minimize equity exposure, and multi-strategy funds blend these approaches. Hedged equity strategies like Swan’s Defined Risk Strategy (DRS) maintain full equity market exposure (85–90% in S&P 500 ETFs) while using actively managed LEAPS put options to mitigate downside risk. The DRS is designed to participate meaningfully in bull markets while managing bear market losses — the ‘always invested, always hedged’ structure that most traditional liquid alternatives don’t achieve.
Q4: What does ‘Always Invested, Always Hedged’ mean?
‘Always Invested, Always Hedged’ is Swan’s description of the DRS’s permanent structure: the strategy maintains continuous equity market exposure (Always Invested) while keeping an active put option hedge in place at all times (Always Hedged). Unlike strategies that add hedges tactically during crises and remove them in recoveries, the DRS is designed as a through-cycle allocation — the hedge is never removed, only actively managed and adjusted.
Q5: How has the Swan DRS performed vs. a liquid alternatives allocation?
In analysis from July 1997 through March 2026 (different from the table shown above), inserting 20% of the Swan DRS into a traditional 60/40 portfolio (replacing equal portions of stocks and bonds, 10% each) as a dedicated sleeve produced an annualized return of 7.62% with a Sharpe ratio of 0.59 — compared to 7.44% and a Sharpe of 0.54 for the traditional 60/40. See the full Zephyr report here. Source: Morningstar Direct, Zephyr StyleADVISOR, Swan Global Investments. Past performance does not guarantee future results.
Q6: Can the Swan Defined Risk Strategy serve as a permanent alternatives allocation?
Swan’s DRS has been in continuous operation since July 1997 — through the LTCM and Russian Debt crises, the Dot-Com Bust, the 2008 Global Financial Crisis, the 2020 COVID crash, the 2022 inflation bear market, and the 2025 tariff-driven selloff. As an ‘Always Invested, Always Hedged’ strategy with meaningful equity upside participation, the DRS is designed to be held through full market cycles rather than adopted tactically. Whether it is appropriate as a permanent alternatives allocation depends on an investor’s specific risk tolerance, time horizon, and existing portfolio construction — this is not individualized investment advice.
Marc Odo, CFA®, FRM®, CAIA®, CIPM®, CFP®, Director of Research and Client Portfolio Manager, is responsible for helping clients and prospects gain a detailed understanding of Swan’s Defined Risk Strategy, including how it fits into an overall investment strategy. His responsibilities also include producing most of Swan’s thought leadership content. Formerly, Marc was the Director of Research for 11 years at Zephyr Associates.
* The Swan Defined Risk Strategy, the Swan DRS, or DRS referred to in this document refer to the Defined Risk U.S. Large Cap Strategy Composite.
Swan Global Investments, LLC is a SEC registered Investment Advisor that specializes in managing money using the proprietary Defined Risk Strategy (“DRS”). SEC registration does not denote any special training or qualification conferred by the SEC. Swan offers and manages the DRS for investors including individuals, institutions and other investment advisor firms.
All investment strategies have the potential for profit or loss. Changes in investment strategies, contributions or withdrawals may cause the performance results of a client’s investment portfolio to differ materially from the reported composite performance. Different types of investments involve varying degrees of risk and there can be no assurance that any specific investment will either be suitable or profitable for a client’s investment portfolio. All Swan products utilize the Defined Risk Strategy (“DRS”), but may vary by asset class, regulatory offering type, etc. Accordingly, all Swan DRS product offerings will have different performance results and comparing results among the Swan products and composites may be of limited use. Economic factors, market conditions, and investment strategies will affect the performance of any portfolio and there are no assurances that it will match or outperform any particular benchmark. Historical performance results for market indices and/or categories generally do not reflect the deduction of transaction and/or custodial charges or the deduction of an investment management fee, the incurrence of which would have the effect of decreasing historical performance results. Swan’s investments may consist of securities which vary significantly from those in the benchmark indexes listed above and performance calculation methods may not be entirely comparable. Accordingly, comparing results shown to those of such indexes may be of limited use. The equity portion of portfolio is hedged using put options and the option income portion of the portfolio is actively managed to seek additional income. Both the equity and income portion of the strategy may experience losses in a market downturn but may be defined and mitigated by the hedge. The extent of potential losses will vary depending on many factors including, but not limited to; the options used, option strategy, expiration, prices, actions taken by portfolio manager. The adviser’s dependence on its DRS process and judgments about the attractiveness, value and potential appreciation of particular ETFs and options in which the adviser invests or writes may prove to be incorrect and may not produce the desired results. There is no guarantee any investment or the DRS will meet its objectives. All investments involve the risk of potential investment losses as well as the potential for investment gains. Prior performance is not a guarantee of future results and there can be no assurance, and investors should not assume, that future performance will be comparable to past performance. Minimum account size is $100,000. Management fee based on account size. For further information, including fee details, please get in touch with a Swan Global Investments representative by contacting the company directly at 970-382-8901 or www.swanglobalinvestments.com. 071-SGI-060526
Global Investment Performance Standards (GIPS®) Report

Performance is presented for the past 10 calendar years as of December 31, 2024. The firm has a longer performance track record for this composite which is available upon request.

Compliance Statement: Swan Global Investments, LLC (“Swan”) claims compliance with the Global Investment Performance Standards (GIPS®) and has prepared and presented this report in compliance with the GIPS standards. Swan has been independently verified by The Spaulding Group for the periods July 1, 1997 through December 31, 2024. The verification report is available upon request.
A firm that claims compliance with the GIPS standards must establish policies and procedures for complying with all the applicable requirements of the GIPS standards.
Verification provides assurance on whether the firm’s policies and procedures related to composite and pooled fund maintenance, as well as the calculation, presentation, and distribution of performance, have been designed in compliance with the GIPS standards and have been implemented on a firm-wide basis. Verification does not provide assurance on the accuracy of any specific performance report. To receive copies please call 970-382-8901 or email [email protected].
Definition of the Firm: Swan Global Investments, LLC is an SEC registered investment advisor providing asset management services utilizing the Swan Defined Risk Strategy (“DRS”), allowing its clients to grow wealth while protecting capital. Please note that registration of the adviser does not imply a certain level of skill or training. Swan Global Investments, LLC is affiliated with Swan Capital Management, LLC, Swan Global Management, LLC and Swan Wealth Management, LLC.
Firm Redefinition: Previously Swan offered and managed The Defined Risk Strategy for its clients which were individual investors. Swan redefined itself to include all client types, including individuals, institutions and sub-advised clients, as of January 1, 2010. This redefinition resulted in a change to Swan’s 2009 performance numbers, due to adding all sub-advised clients beginning on June 30, 2009. Additionally, Swan created affiliated entity Swan Capital Management, Inc. on April 13, 2012 to be an advisor and distributor of the Swan Defined Risk Fund launched in July 2012. In December 2014, Swan Capital Management, Inc. converted to Swan Capital Management, LLC. Swan created affiliated entity Swan Wealth Management, LLC to serve as the portfolio manager of the DRS in 2014, and subsequently created affiliated entity Swan Global Management, LLC to serve as the portfolio manager of the DRS starting in 2015.
Name Changes: Swan Consulting, Inc. changed its name to Swan Wealth Advisors, Inc. on April 8, 2011 to better reflect that the Company is a money management firm. Investment consulting firms generally do not manage money. Swan Wealth Advisors, Inc. changed its name to Swan Global Investments, LLC on December 5, 2014 to better reflect that the Company is a money management firm rather than an advisor. Advisors are the Company’s clients, and it does not want to give the impression that the Company is competing with other advisors. Instead, Swan Global Investments, LLC offers investment products and manages money for sub-advised clients and the mutual funds of its affiliate Swan Capital Management, LLC.
Composite Inception Date: The inception of the DRS U.S. Large Cap Composite was July 1, 1997.
Composite Creation Date: The DRS U.S. Large Cap Composite was defined on January 1, 2010.
Composite Description: The DRS U.S. Large Cap Composite demonstrates the performance of qualified and non-qualified assets invested in DRS U.S. Large Cap strategies managed by Swan Global Investments, LLC since inception. It includes discretionary individual accounts whose account holders seek the upside potential of owning stock, and the desire to minimize the downside risk associated with owning stock. The Composite relies on LEAPS and other options to manage this risk. Individual accounts own S&P 500 exchange traded funds and LEAPS associated with the exchange traded funds as well as multiple other option trades that represent other indices that are widely traded. The Defined Risk Strategy was designed to protect investors from substantial market declines, provide income in flat or choppy markets, and to benefit from market appreciation. Stock and options are the primary components of the strategy. Portfolios in the composite may include non-DRS securities (securities that are not part of the Swan Defined Risk Strategy) that are excluded from composite performance.
Returns: Performance results reflect the reinvestment of dividend and other earnings and are expressed in U.S. dollars. Gross-of-fee performance results do not reflect the deduction of the firm’s investment management fees or custodial fees but are net of all transaction costs and withholding taxes (if applicable). Net-of-fees returns are calculated by deducting the higher of either actual management fees or a model management fee equal to the highest tier of the fee schedule (0.60% annual, or 0.05% monthly) from the monthly gross-of-fee composite return. The composite includes portfolios that pay zero commissions on certain securities in the portfolio (e.g., exchange traded funds (ETFs)).
Fee Schedule: The investment management fee schedule for sub-advised clients is as follows. Rate breaks are applied to total aggregate assets under management under the sub-advisory agreement:
Annual fees are 60 basis points (0.60%) on the first $10 Million; 50 basis points (0.50%) on the next $190 Million; 45 basis points (0.45%) on the next $300 Million; 40 basis points (0.40%) on the next $500 Million; and 35 basis points (0.35%) over $1 Billion. Actual investment management fees incurred by clients may vary.
Benchmark: The benchmarks used for The DRS U.S. Large Cap Composite is the S&P 500 Index, which consists of approximately 500 large cap stocks and 60%/40% blended benchmark consisting of 60% S&P 500 Index and 40% Bloomberg US Aggregate Bond Index, a broad-based flagship benchmark that measures the investment grade, US dollar-denominated, fixed-rate taxable bond market. The index includes Treasuries, government-related and corporate securities, MBS (agency fixed-rate and hybrid ARM pass-throughs), ABS and CMBS (agency and non-agency).
Policies: Policies for valuing investments, calculating performance, and preparing GIPS reports, as well as a complete list and description of composites and broad distribution pooled funds are all available upon request.
Use of Derivatives: The purchase and sale of options are a component of The Defined Risk Strategy Composite. Options are traded on both long-term and short-term horizons to reduce the risk of owning stock and to generate income. Since inception of The Defined Risk Strategy, options have been responsible for a significant portion of total returns. The DRS uses little or no leverage (<2% of total portfolio value). Portfolios are generally balanced annually with approximately 85-90% stock, 10-15% options. Please contact Swan Global Investments, LLC for more detailed information on the use of options in The DRS.
Leverage and Short Positions: The DRS U.S. Large Cap Composite uses a combination of ETFs (long) and options, both long (portfolio has bought a position in a call or put option) and short (the portfolio holds a written call or put option) positions which constitute approximately 85-90% and 10-15% of the portfolio, respectively. The Defined Risk Strategy does not typically borrow money to buy stock on margin and as a result does not use leverage in the traditional sense. However, the DRS uses options as a material part of the strategy and by definition may constitute use of leverage since options typically control a large amount of the underlying security. This does not imply that The DRS portfolio is leveraged. The short option positions that are used to generate income are offset in whole or in part by the long stock and long options positions contained in the portfolio. Regardless, a margin account could be required.
Minimum account size: Before January 1, 2013, there was no minimum account size required for inclusion in Defined Risk Strategy Composite. Starting January 1, 2013, the minimum account size required for inclusion in the DRS U.S. Large Cap Composite is $250,000.
Beta: Beta for the Composites has been calculated using the standard formula of: covariance of portfolio and benchmark returns divided by the variance in benchmark returns. The period used in calculations is July 1, 1997 through the end of the period and the frequency of returns used is monthly. Beta is based on returns that are net of Swan fees only. A beta greater than 1.0 indicates that the investment is more volatile than the index, whereas a beta between 0 and 1.0 indicates that the investment is less volatile than the market index. A negative beta indicates the investment performance is counter-cyclical to the market. Values are excluded for the first 3.5 years of Composite implementation (i.e., 1997-2000) to ensure sufficient measurement points for meaningful statistical analysis.
Standard Deviation (External): Standard deviation measures the variability of the Composite’s monthly returns, and states that variability on an annualized basis. Annualized standard deviations of monthly returns for both the Composite and benchmark have been calculated using the following method: Standard Deviation of 36 monthly returns multiplied by the Square Root of 12 (which annualizes it). This measure is based on returns that are net of Swan fees only.
Measure of Dispersion (Internal Standard Deviation): The Composite dispersion is measured using standard deviation of returns as stated above. However, from inception to December 31, 2012, the dispersion represented the variability of Net-of-Fees returns within the Composite. After December 31, 2012, the dispersion represents the variability of Gross-of-Fees returns within the Composite to remove the variance in fees per account. Dispersion is measured using only portfolios that were included in the Composite the entire calendar year.
Sharpe Ratio: Sharpe Ratios for both the Composite and the benchmark have been calculated using the standard formula of (Annualized Return – Risk Free Annualized) / Standard Deviation. The period used in calculations is July 1, 1997 through the end of the period and the frequency of returns used is annually. Annualized Returns in this calculation are net of Swan fees only. Risk Free Return values used in calculations are based on 91 Day Treasury Bill returns for the same period. Values are excluded for the first 3.5 years of Composite implementation (i.e., 1997-2000) to ensure sufficient measurement points for meaningful statistical analysis.
Currency: All valuations are computed, and performance reported in US dollars. Past results do not guarantee future performance.
Portfolios in the composite may include non-DRS securities (securities that are not part of the Swan Defined Risk Strategy) that are excluded from composite performance.
GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein.
095-SGI-081426